Financial Socialization in Christian Households
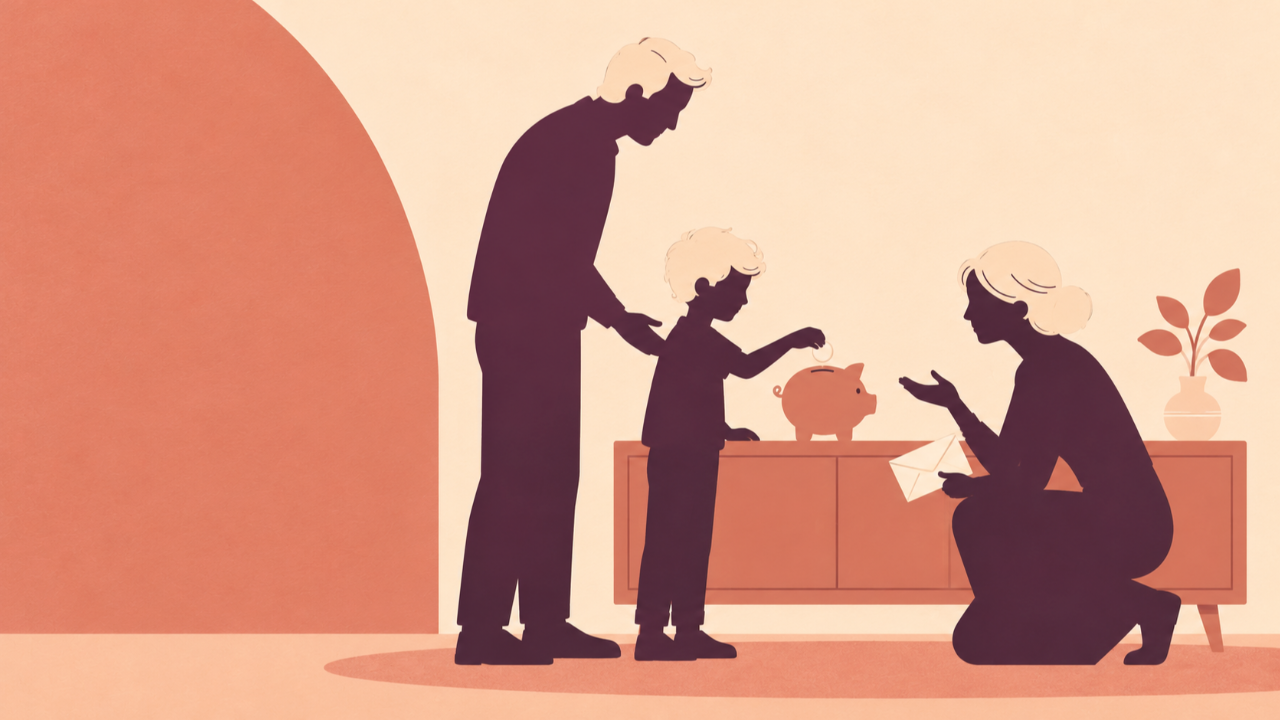
A child’s financial education begins long before opening a bank account or receiving a first paycheck. It develops through everyday experiences: watching parents make purchases, hearing conversations about bills, and observing how a household responds to opportunities for generosity.
Researchers describe this process as financial socialization, the development of money-related knowledge, attitudes, values, and behaviors through social interaction. For Christian households, it raises an important question:
How can families intentionally prepare children to manage money while helping them understand its purpose?
Answering that question requires attention to both empirical research and biblical teaching.
Understanding the Family’s Role
Gudmunson and Danes’s family financial socialization framework places financial learning within the broader context of family relationships, personal characteristics, and household circumstances. Their approach recognizes that financial development involves more than transferring information. The environment in which children learn also matters.
LeBaron and Kelley’s review identifies three principal methods of financial socialization: parental modeling, parent-child financial discussion, and experiential learning. Together, these describe how children observe financial behavior, receive explanations, and practice managing resources. The literature connects these processes with financial attitudes, behaviors, and well-being, although findings vary across studies.
For Christian families, these methods offer a useful framework for applying stewardship principles. The application, however, should be distinguished from the research itself. Evidence about families generally does not automatically establish outcomes specific to Christian households.
Parental Modeling: What Children Observe
Children have opportunities to observe how parents handle competing priorities. They may see a parent delay a purchase, compare prices, make a charitable contribution, or respond to an unexpected expense.
The research reviewed by LeBaron and Kelley linked parental financial modeling with emerging adults’ financial attitudes and behaviors. These associations suggest that parents’ actions deserve attention alongside their verbal instruction.
The Christian implication is straightforward: stated beliefs about money should be reflected in observable decisions.
Parents who teach generosity can explain how giving fits into the household’s financial plan. Those who encourage contentment can acknowledge their own desires while demonstrating thoughtful spending limits.
This does not require financial perfection. A parent can acknowledge an unwise purchase and explain the corrective action being taken. Such conversations provide opportunities to demonstrate honesty, responsibility, and humility.
Financial Discussion: Explaining the Reasons
Observation alone leaves room for misunderstanding. A child may see a parent decline a purchase without understanding whether the decision reflects limited resources, a savings goal, or a different priority.
Age-appropriate discussion makes the reasoning visible.
Parents might explain why the family saves before making a larger purchase, how a spending plan supports household responsibilities, or why giving receives an intentional place in the budget.
Deuteronomy 6:6–7 presents instruction in God’s commands as part of ordinary family life. Although the passage is not specifically about financial education, it provides a theological basis for integrating biblical instruction into daily experiences.
A shopping trip can become an occasion to discuss contentment. A giving decision can prompt conversation about loving neighbors. The objective is to connect practical choices with a coherent understanding of stewardship.
Experiential Learning: Providing Opportunities to Practice
Children also need manageable opportunities to make decisions themselves.
Examples include dividing gift money among giving, saving, and spending; comparing options within a fixed budget; or saving toward a purchase over several weeks.
Experiential learning is recognized in the financial socialization literature as a distinct method through which families teach children about money.
For Christian households, practice can include generosity. A child might choose a cause to support, contribute toward a church offering, or help plan an affordable act of hospitality.
Parents should provide guidance while allowing appropriate consequences. Spending discretionary money quickly may mean waiting before another purchase. The experience becomes more useful when parents help the child reflect without ridicule.
Implications for Churches and Counselors
Churches and Christian financial counselors can equip parents with conversation prompts, practical activities, and accessible financial education. Support should accommodate households with different resources.
Future research should examine how religious instruction, observed generosity, and everyday financial practices interact within Christian families.
The goal is to help children develop financial competence alongside an understanding of accountability to God. Modeling, conversation, and guided practice provide concrete places to begin.