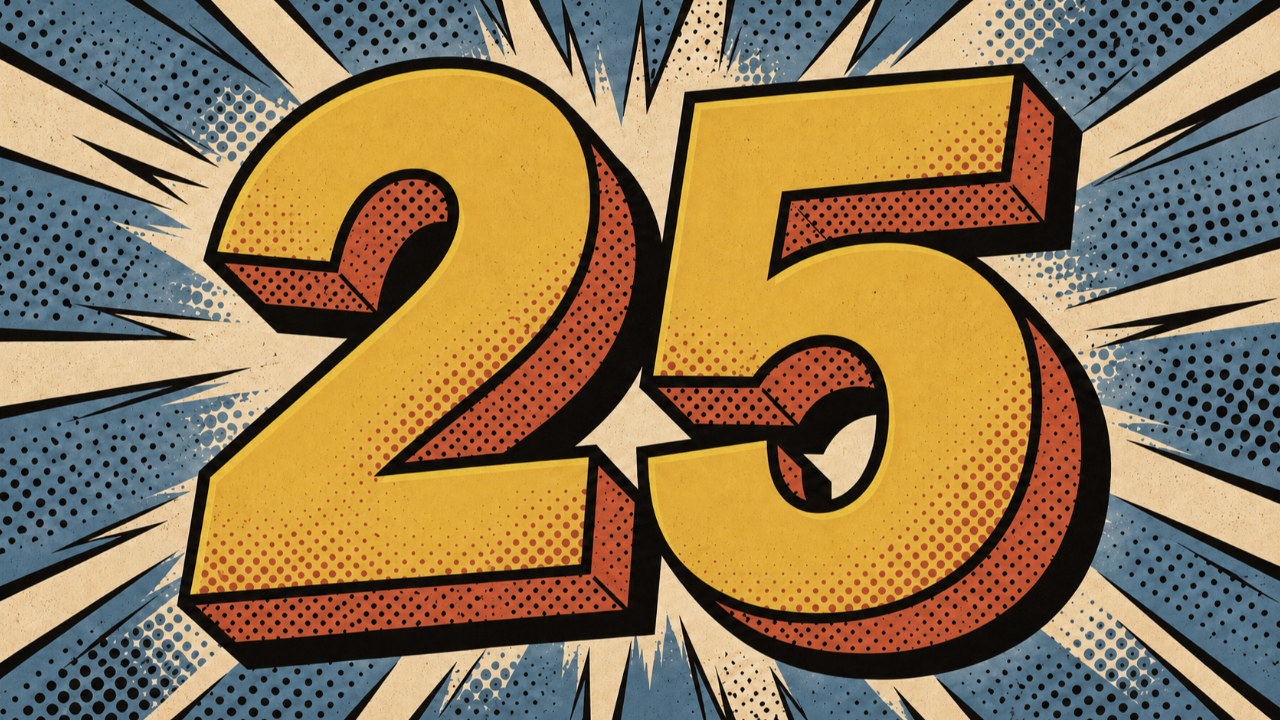
The Rule of 25: A Simple Way to Estimate Your Retirement Needs
The Rule of 25 is a guide, not a guarantee. It can help you estimate a retirement savings target, but it cannot promise that your money will last. Your expenses, investments, taxes, and retirement length all matter.
With that understood, this simple calculation can bring clarity to a question many people find overwhelming:
“How much money do I need to retire?”
You hear someone mention $1 million. Someone else says $2 million. Suddenly, retirement feels like a finish line that keeps moving farther away.
The Rule of 25 offers a starting point by connecting your savings goal to the expenses your investments will need to cover.
What is the Rule of 25?
The Rule of 25 estimates your retirement savings target by multiplying the annual amount you need from your investments by 25.
Here’s the formula:
Annual expenses your investments must cover × 25 = Estimated savings target
If you need your investments to provide $20,000 annually, the calculation produces a $500,000 target. If you need $30,000, the target becomes $750,000.
This guideline is connected to the familiar 4% rule. Twenty-five times an annual withdrawal produces a portfolio from which that withdrawal represents 4%.
The traditional 4% approach involves withdrawing 4% of your starting portfolio during your first retirement year, then adjusting that dollar amount for inflation in subsequent years. It was designed around a roughly 30-year retirement.
Remember the income you already expect.
A common mistake is multiplying all retirement expenses by 25 without accounting for Social Security or a pension. Those income sources can reduce the amount your investments need to provide.
Imagine that your retirement budget totals $4,000 monthly, or $48,000 annually. For this simplified example, assume that amount includes anticipated taxes.
Now suppose Social Security will provide $2,500 monthly, or $30,000 annually.
Your investments would need to cover the remaining $18,000 each year.
Multiply $18,000 by 25, and your estimated savings target becomes $450,000.
That is a very different number from the $1.2 million you would calculate by multiplying your entire $48,000 budget by 25.
Your retirement income gap matters.
Small expense reductions can have a meaningful impact.
The Rule of 25 also helps explain why reducing ongoing expenses can strengthen your retirement outlook.
Suppose paying off a debt permanently eliminates a $300 monthly payment. That reduces your annual expenses by $3,600.
Multiply $3,600 by 25, and the estimated savings needed to support those expenses falls by $90,000.
You haven’t added $90,000 to your account. You have reduced the amount your account needs to support.
This is one reason entering retirement without debt can be so helpful. Lower recurring expenses can create more breathing room in your monthly budget.
Consider what the formula cannot capture.
Market performance, investment choices, inflation, taxes, fees, healthcare costs, and retirement length affect the outcome. Someone retiring early may need savings to support substantially more than 30 years.
Your spending and income may also change. A pension may not increase with inflation. A surviving spouse’s income may differ from what the couple previously received.
A qualified financial professional can help you evaluate these variables.
Let the number lead to action.
Estimate your retirement expenses. Identify reliable income sources. Calculate the gap. Then explore how saving more, reducing expenses, or adjusting your retirement timing could improve your position.
As Christians, we can approach this process as stewardship, thoughtfully preparing to use God’s resources for the years ahead.
You don’t need a formula to predict your future perfectly. You need useful information that helps you take your next faithful step.